More conversations I’m having with clients, colleagues and friends in the DMV now include a question I rarely heard a decade ago:
What do we do with the house if we move overseas?
The people asking aren’t simply daydreaming about a listing they saw in Lisbon or a villa in Spain. They include retirees with substantial equity, federal and military households, remote professionals, and couples considering spending a few years abroad before deciding what comes next.
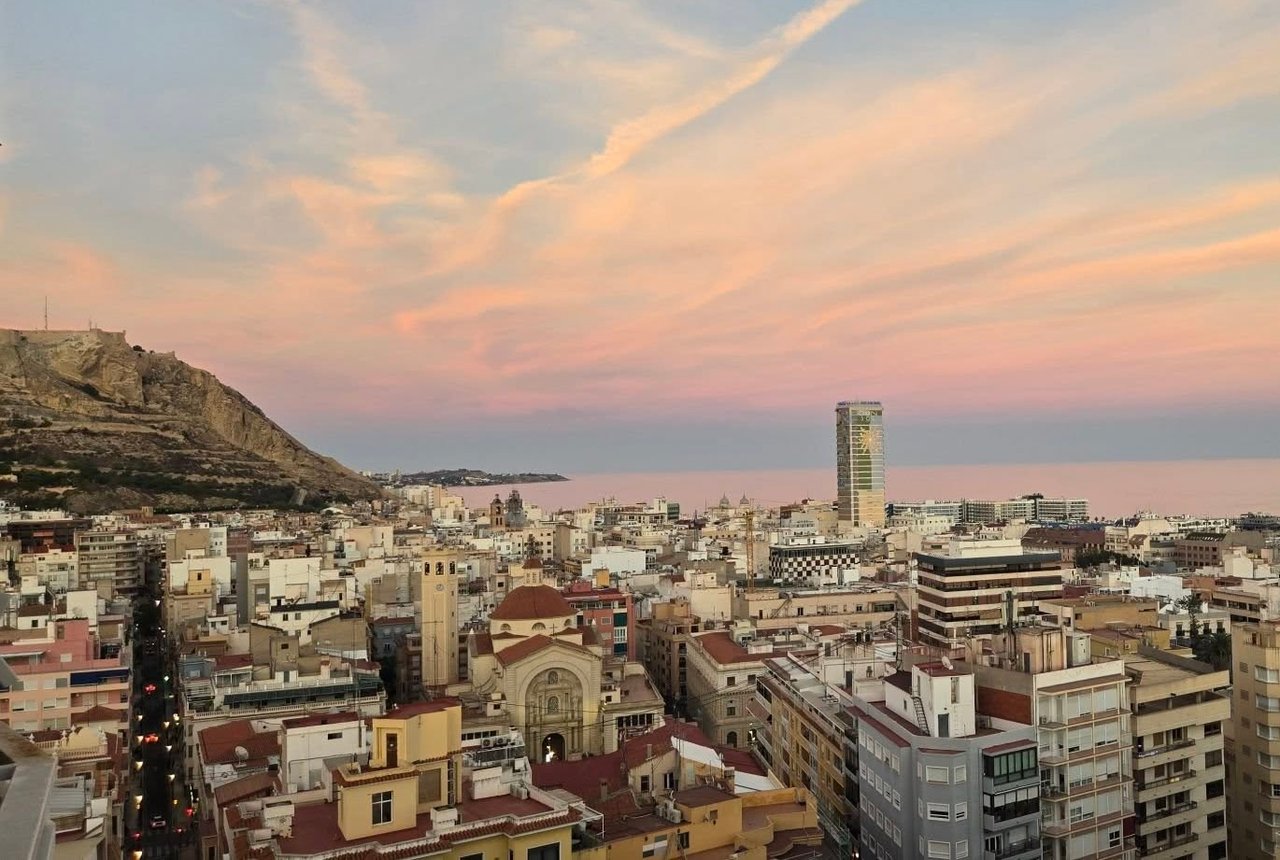
I’m asking some of those same questions myself as I consider a possible move to Spain. A recent week in Alicante gave me a closer look at the practical issues behind an international move: housing, equity, taxes, healthcare, family — and the very real difference between visiting a place and actually living there.
For many homeowners, moving abroad is the life decision.
What happens to the home you already own may be the financial decision that makes it possible.
More Americans are considering life abroad
It’s surprisingly difficult to know exactly how many Americans live overseas because the U.S. government doesn’t maintain a comprehensive count of citizens once they relocate. The Association of Americans Resident Overseas estimates the number at roughly 5.5 million.
What we can measure more clearly is interest.
Gallup reported in 2025 that about one in five Americans said they would move permanently to another country if they had the opportunity. Interest doesn’t necessarily translate into an actual move, of course. But it does tell us that living abroad has moved from an occasional fantasy into a serious conversation for a meaningful number of Americans.
Here in the DMV, I think that conversation has some unique dimensions.
We have federal employees, military families and diplomats who may already have international experience. We have retirees sitting on decades of home equity. And we have professionals whose work may no longer require them to be in the same city — or even the same country — every day.
For homeowners, though, deciding where to go is only half of the conversation.
The other question is what to do with the house.
Should you sell, rent or keep your U.S. home?
There isn't one right answer.
I’d start with two questions:
How certain are you that the move will be permanent?
And:
What role does the equity in your current home need to play in making the move possible?
Selling before you leave
Selling may make sense if you're confident about the move, don't want to manage a rental from another country, or need the equity to purchase a home abroad.
For longtime DMV homeowners, that equity can be substantial. Selling can turn an illiquid asset into the flexibility to buy abroad, invest differently or simply begin the next chapter with fewer financial obligations back home.
But before listing the house, talk to a qualified tax professional.
Under current IRS rules, homeowners who meet the eligibility requirements may exclude up to $250,000 in gain — or up to $500,000 for qualifying married couples filing jointly — from the sale of a primary residence. Generally, you need to have owned and lived in the property as your main home for at least two of the five years before the sale. The IRS explains the home-sale exclusion in Publication 523.
That timing can become important if you're thinking about renting the home for several years before selling.
Renting the home
Renting can provide a useful bridge if you're not ready to make the move permanent.
Maybe you want to spend two years in Spain and see how it feels. Maybe you're on an overseas assignment. Or perhaps you have an excellent mortgage rate and aren't ready to give it up.
Keeping the property allows you to maintain a foothold in the U.S. while someone else helps offset the carrying costs.
But being a landlord from another continent isn't passive income in the truest sense of the word.
You'll need to think about property management, repairs, vacancies, tenant screening, insurance and taxes. And U.S. citizens generally remain subject to U.S. tax rules on worldwide income, including applicable rental income, even while living abroad. The IRS provides guidance for U.S. citizens living overseas.
Keeping it as your U.S. home base
There's also a middle ground.
Some people simply keep their home.
That can make sense if you expect to divide your time between countries, have family in the U.S., or aren't ready to give up the security of having a familiar place to return to.
The trade-off is obvious: you're carrying the expenses of a home you may only use part of the year.
The question becomes whether the flexibility is worth the cost.
One important exception for DMV military and federal households
There’s a provision that some Washington-area homeowners should know about.
Certain members of the Uniformed Services, Foreign Service and intelligence community serving on qualified extended duty may be able to suspend the normal five-year testing period used for the home-sale exclusion.
That suspension can last as long as 10 years in qualifying circumstances.
For someone stationed overseas for several years, that can make an enormous difference in deciding whether to keep or sell a home. The IRS explains the applicable rules here.
This is exactly the kind of issue I'd want a homeowner to discuss with a tax professional before making the real estate decision rather than discovering it afterward.
Should you buy or rent when you get there?
This is where my own experience in Alicante changed some of my thinking.
It's easy to look at overseas property prices and immediately start doing the math.
But buying property in another country and having the legal right to live there are two different things. Owning a home generally doesn't automatically give you residency. Visa and residency requirements are separate and vary considerably from country to country.
More importantly, I'm increasingly convinced that there's tremendous value in living somewhere before buying there.
On my trip to Alicante, I met a couple who had purchased fairly quickly after arriving. They later decided to sell because the neighborhood didn't fit the life they wanted.
There was nothing particularly wrong with the home.
The location simply wasn't right for them.
That stuck with me because it's the same conversation I have with buyers here in the DMV. A beautiful kitchen won't compensate for a neighborhood that doesn't support the way you want to live.
Renting first gives you time to understand the things you can't fully appreciate during a scouting trip: morning traffic, neighborhood noise, public transportation, healthcare access, grocery shopping, summer heat and what Tuesday afternoon feels like when you're no longer on vacation.
What I learned from Alicante
My September trip reinforced something I already believe about real estate: lifestyle should come before features.
Alicante's walkability and tram system made everyday errands remarkably easy without a car. That matters to me.
But I also noticed smaller housing details I wouldn't necessarily have considered from Washington. Central air conditioning, for example, isn't as universal as many Americans might expect. In a Mediterranean summer, that's not a minor detail.
I also started thinking differently about what a workday could look like. For someone maintaining some U.S.-based work, the time difference can shift the business day later, leaving more of the daytime available for language classes, errands, exercise or simply experiencing the city.
Those aren't necessarily things you'll find on a property listing.
But they're absolutely part of deciding whether a place works for your life.
How does your U.S. home help fund the move?
For homeowners with significant equity, the current home often becomes part of the funding strategy.
That doesn't automatically mean selling it.
Depending on the household's financial position, possibilities can include selling and using the proceeds, borrowing against U.S. home equity, using other investment assets, or obtaining financing in the destination country.
Each comes with different risks.
Borrowing against a U.S. property means continuing to carry debt in dollars. Financing overseas can involve different underwriting requirements, larger down payments and currency considerations. Selling provides liquidity but also means giving up the U.S. property and any favorable financing attached to it.
This is one area where I wouldn't make the real estate decision in isolation.
A financial advisor, CPA, lender and real estate advisor should be looking at the same picture.
Don't overlook healthcare, taxes and estate planning
The house tends to get most of our attention because it's tangible. But an international move affects much more than real estate.
A few conversations belong on the planning list early:
Taxes. Moving abroad doesn't automatically end your U.S. tax obligations. U.S. citizens generally remain subject to U.S. tax rules on worldwide income. The IRS has a dedicated resource for Americans living abroad.
Healthcare. This is particularly important for retirees. Medicare generally doesn't cover routine healthcare outside the United States, except in limited circumstances. Medicare explains its international coverage rules here.
Estate planning. A U.S. will or trust may interact with very different inheritance, marital-property and probate rules in another country. Cross-border estate planning deserves specialized legal advice.
Currency. If your assets and income are primarily in dollars but your new home and living expenses are in euros or another currency, exchange-rate changes become part of your household budget.
None of these issues means you shouldn't move.
They simply mean the move deserves a plan.
Start with the home you know
When people imagine moving abroad, it's natural to begin with the destination.
Spain. Portugal. France. Mexico.
I'd begin one step earlier.
Start with the home you already own.
What is it worth today? What could it realistically rent for? How much equity do you have? What would it cost to keep? What tax considerations could affect the timing of a sale? And, perhaps most importantly, what would each option make possible for the life you're trying to build?
For homeowners in Washington, D.C., Northern Virginia and Maryland — particularly retirees, federal employees, diplomats and military families — those answers can help shape everything that comes next.
I'm exploring some of these questions personally as I consider what living in Spain could eventually look like for me. And the more I learn, the clearer one thing becomes:
Going global doesn't necessarily start overseas. Sometimes it starts with making a thoughtful decision about the home you're leaving behind.
This article is for general informational purposes and isn't tax, legal, financial or immigration advice. Consult qualified professionals in the United States and your destination country before making decisions specific to your circumstances.